Bank Statement Loans: The Self-Employed Investor's Guide to Non-W2 Mortgages
Traditional mortgage underwriting was built around W-2 employees with steady paychecks and tidy tax returns. But for self-employed real estate investors, business owners, and 1099 earners, qualifying for conventional financing can feel like hitting a wall. That's where bank statement loans come in — a flexible non-QM product designed to qualify borrowers on the strength of their actual cash flow, not their tax returns.
In this guide, we'll break down how bank statement loans work, who they're built for, what you'll need to qualify, and how they compare to other investor financing options.
What Is a Bank Statement Loan?
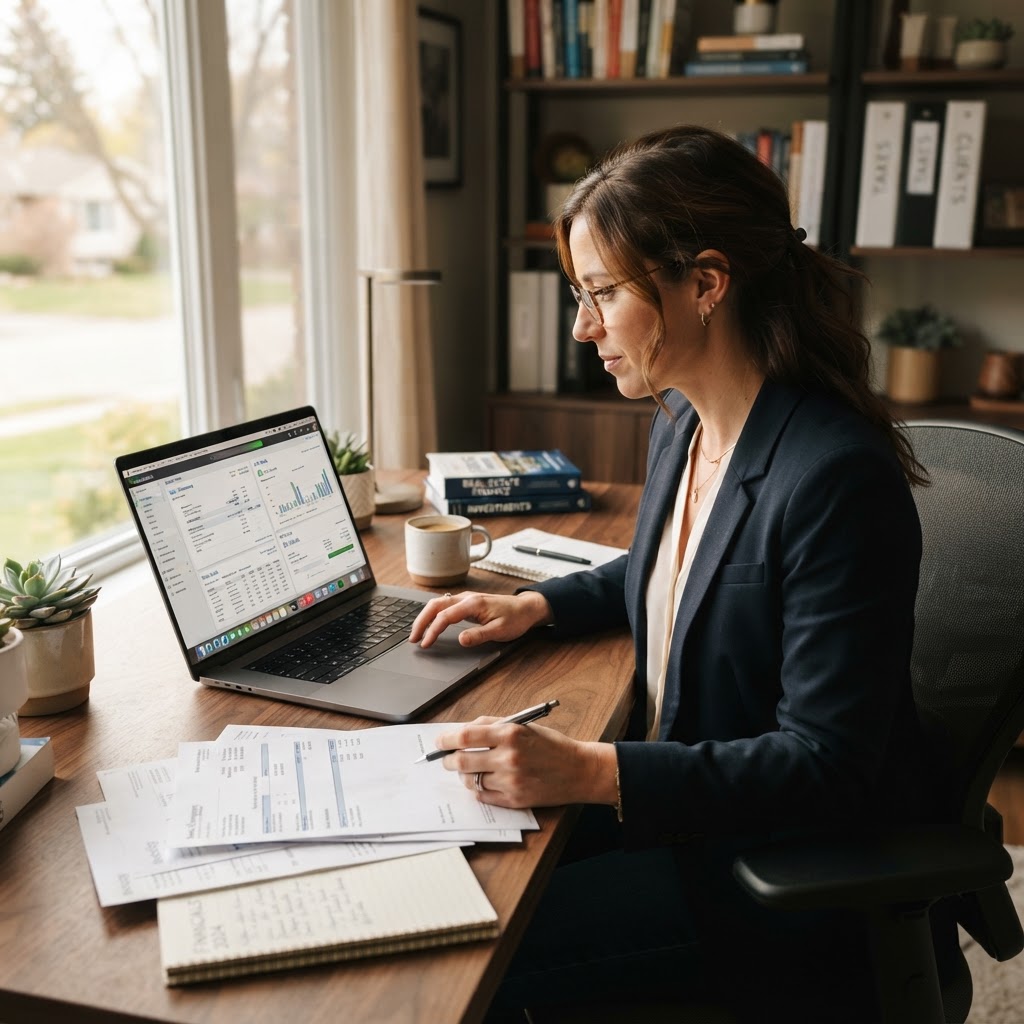
A bank statement loan is a non-qualified mortgage (non-QM) that uses your personal or business bank deposits — typically over the past 12 to 24 months — to calculate qualifying income instead of tax returns, W-2s, or pay stubs. The lender averages your monthly deposits, applies an expense ratio (often 50%), and uses the resulting figure to underwrite the loan.
This makes bank statement loans ideal for borrowers who show significant write-offs on their tax returns but maintain strong real cash flow.
Who Benefits from Bank Statement Loans?
Bank statement loans are built for borrowers whose true earning power isn't reflected on a tax return:
- Self-employed investors with multiple LLCs or properties
- Business owners who deduct aggressively to lower taxable income
- 1099 contractors and freelancers without a traditional employer
- Real estate professionals whose income flows through operating accounts
If your tax returns make you look like you earn less than you actually do, a bank statement loan can unlock financing a conventional lender would deny.
Typical Bank Statement Loan Requirements
While every lender sets their own overlays, expect to provide:
- 12–24 months of bank statements (personal or business)
- A minimum credit score, commonly 660+
- A down payment, typically 20–25% for investment properties
- Proof of business ownership (for business bank statement programs)
- A property appraisal supporting the purchase or refinance
Debt-to-income is calculated differently here — the lender derives your income from deposits rather than a W-2, then weighs it against your monthly obligations.
Bank Statement Loans vs. DSCR Loans
Both products serve investors, but they qualify differently. A DSCR loan qualifies the property based on rental income covering the debt, while a bank statement loan qualifies the borrower based on personal cash flow. Many investors use both across their portfolio — DSCR for cash-flowing rentals and bank statement loans for properties where personal income strength matters most.
Interest Rates and Costs
Because bank statement loans carry more risk for the lender, expect rates roughly 1–3% above conventional mortgage rates, plus a slightly higher down payment. The trade-off is flexibility: you gain access to financing that conventional underwriting would never approve.
How to Apply
Ready to see if a bank statement loan fits your portfolio? Start an application and our team will review your bank statements, property details, and financing goals to match you with the right program. You can also explore our investment property loan options or review the documents you'll need.
Frequently Asked Questions
Are bank statement loans more expensive than conventional mortgages?
Yes — typically 1–3% higher in rate, plus a larger down payment, because the lender is taking on non-traditional income verification risk.
Can I use a bank statement loan on an investment property?
Yes. Bank statement loans are commonly used for investment properties, and many borrowers pair them with hard money or private money for short-term acquisitions.
How many months of bank statements do I need?
Most lenders require 12 months, with some programs requesting 24 months for a stronger income average.